Buying property at an interest rate of 7% is financial suicide unless you know how to use assumable mortgage loans. The usual advice to buy and refinance is a total scam sold by desperate loan officers trying to meet their monthly targets. Doing this permanently damages your cash flow because you pay twice the interest rate of an informed investor who knows how to navigate the current market.
A few months ago, my close friend Zain, who runs an elite real estate advisory business called Dextify Consulting, asked me to review a badly executed transaction. He was advising a high-net-worth client who wanted to buy a 12-unit multi-family property in Texas. At current market rates, the figures were dreadful; with a 7.5% commercial loan, the property was producing negative cash flow of $2,400 per month. The earlier brokerage firm tried to push the deal through by proposing unreasonably high rent increases over the next five years.
Zain halted the transaction right away. He redirected his client’s search to properties with existing government-supported debt originated between 2020 and 2021. By locating and completing a legal loan assumption, Zain enabled his client to take over the seller’s 2.9% interest rate. This one strategic action immediately turned a negative cash-flow obligation into a cash-producing asset that yields a net profit of $3,100 each month.
Zain’s ability to save his client from financial ruin had a strong impact on me. To help our own agency avoid catastrophic figures and falling into the high-rate trap, we developed the Dixtify Free Calculator. This internal tool quickly compares conventional financing with the exact amortization schedule of a loan assumed to have a low rate. I am making it available free of charge today because basing a purchase on hope, and buying cash-flow negative property, will almost certainly lead to bankruptcy. You must protect your capital with rigorous math.
The Financial Bloodbath of 7% Interest Rates
To understand the power of taking on a mortgage, you must review basic amortization calculations. While most people buying property focus only on the purchase price, sensible investors focus on the capital needed to obtain the property.
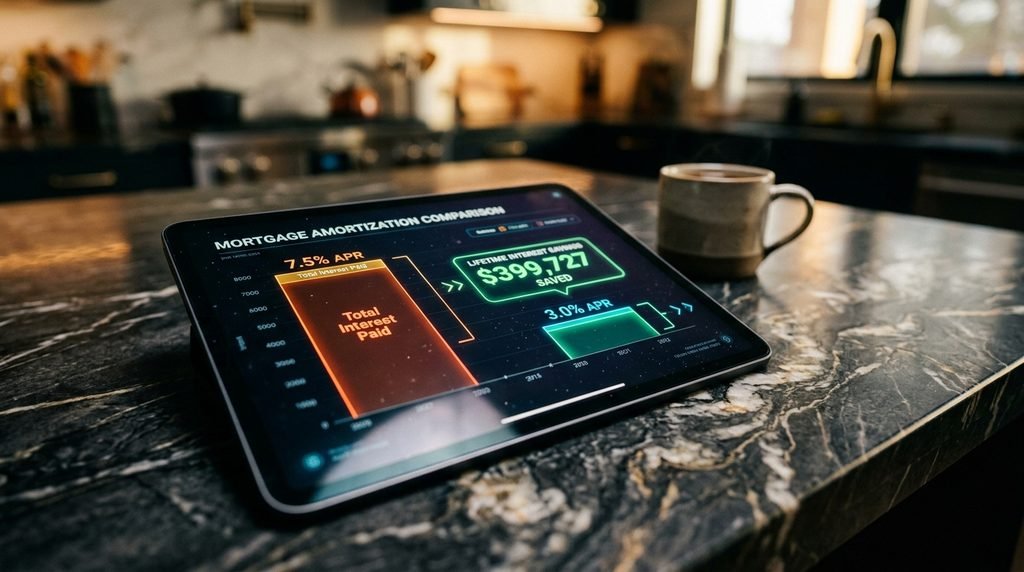
Take the case of a normal $500,000 loan which is amortized over 30 years; at an interest rate of 7.5 percent, your monthly payment for principal and interest will be about $3,496, and over the whole term of the loan you will end up paying the bank a huge amount of $758,000 in interest.
If you take out assumable mortgage loans to get a 3% rate on the same $500,000 balance, your monthly payment will drop to $2,108, saving you almost $1,400 in liquid cash each month. Moreover, the total interest you pay over 30 years will drop to just $258,000; that’s half a million dollars more wealth you keep.
Table of Contents
Understanding the Mechanics of Assumable Mortgage Loans
When you take over a mortgage, you aren’t getting a new loan from the bank at this year’s high interest rates. Instead, you assume the seller’s position and take on their identical loan terms. You inherit their low interest rate, outstanding loan balance, and current repayment schedule.
That is, if the seller obtained a 3 percent rate four years ago and has 26 years remaining on the mortgage, you will have a 3 percent fixed rate for the next 26 years and can avoid the rapid interest rate increases set by the Federal Reserve.
You can’t apply this strategy to every type of property since the vast majority of conventional loans include a strict ‘due-on-sale’ clause. This clause gives the lender the legal right to demand full repayment of the loan balance as soon as the property changes hands. Therefore, you need to look for specific kinds of government-supported debt that legally exclude this clause.
FHA Assumable Loans and Government Backing
The best types of property for today’s real estate investment strategies are those financed with FHA, VA, and USDA loans. Under federal law, these mortgages are fully assumable, and the lender must permit the transfer as long as the new buyer meets its standard credit and income underwriting requirements.
Right now, FHA assumable loans are especially advantageous because millions were issued between 2020 and 2022. Many homeowners today have these mortgages at very low rates. Because FHA loans are usually easier to qualify for than conventional loans, the underwriting process for assuming them is a bit more lenient for investors with complicated tax returns.
The VA Loan Entitlement Trap
VA loans are also legally assumable, but this presents a serious problem for the seller. Because the seller’s military entitlement secures these loans, you can take over the loan even if you’re not a veteran; the seller’s VA entitlement will remain tied to the property until the debt is fully paid off.
Well-educated veterans won’t let a non-veteran take over their loan because it would prevent them from using their VA benefits when buying their next home. As a veteran buying a property and taking over an existing veteran’s loan, you can exchange your entitlement for theirs, making the transaction easier.
Conquering the Equity Gap: The Real Challenge
This approach isn’t a magic solution for inexperienced buyers who have no capital. The main difficulty with assumable mortgage loans is meeting the seller’s equity gap, since you take on only the outstanding loan balance, not the current market purchase price.
For instance, where a seller puts their house up for sale at $600,000 but only have a mortgage of $400,000 to the bank there is an equity gap of $200,000; you, as the buyer, have to provide that $200,000 to the closing table and the seller still needs their cash equity to leave the transaction and purchase their next house.
Most ordinary homebuyers can’t make these assumptions because they don’t have large amounts of liquid cash. To play this game well, you either need substantial capital or you need to be very creative.
Structuring Equity Gap Financing
If you don’t have hundreds of thousands of dollars in a checking account, you’ll need to obtain second financing to cover the difference. Some specialized lenders can give you a second mortgage to cover the difference between the purchase price and the assumed loan balance.
Second mortgages carry current market rates, usually between 8% and 11%, since they come after the first lender in the hierarchy. To ensure the entire transaction remains profitable, you must run a blended-rate calculation.
You may also arrange for the seller to provide financing to cover the equity gap. In this arrangement, the seller acts as a bank for their $200,000 equity, and you agree to pay an interest rate negotiated over five to ten years. If you would like professional advice on how to structure complicated real estate acquisitions or on analyzing your agency’s cash flow, you can look at our custom growth strategies here: [Insert Internal Link to Dixtify Services].
Why Desperate Sellers Agree to This Strategy
You might ask why a seller would let a stranger take over their mortgage at a low interest rate rather than selling the normal way. The reason is a stagnant market. The affordability crisis currently paralyzes the housing market.
Retail buyers can’t afford monthly payments at 7%, so properties stay on the market for months. As recent economic data published by Forbes shows, housing inventory remains frozen mainly because current homeowners refuse to give up their historically low rates and buyers cannot afford the new ones.
A seller can immediately attract many well-qualified, eager buyers by promoting the property with an assumed low interest rate. This lets them ask for a premium purchase price that is not open to negotiation. Buyers will pay more than the asking price to secure an interest rate below 3%.
Navigating the Bureaucratic Nightmare
You should not ask your local loan officer to assist you in finding or arranging these deals. Loan originators earn their commissions by arranging new loans, not by handling assumptions. They will try to persuade you that taking over a mortgage is too difficult, risky, or time-consuming.
The assumption process is notoriously slow and extremely bureaucratic. You have to deal directly with the mortgage servicer who currently serves the seller. The paperwork is tedious, and banks delay because they lose money by letting you keep a 3% rate in a 7% interest-rate environment.
To close the deal, you need to be aggressively proactive. Follow up every day, ask for managerial escalations, and prepare for a closing timeline of 60 to 120 days. The servicer will deliberately let the file expire if you lack patience or organizational skills, and you will lose the asset.