To pay a flat self-employment tax of 15.3% on every single dollar of your net profit is a beginner’s error. When your digital business is producing substantial revenue and you’re still running as a standard single-member LLC, you’re in effect destroying your capital. The usual suggestion of deducting your laptop and internet expenses is entirely inadequate. You need to use the S-Corp tax loophole to radically restructure your tax responsibilities and safeguard your margins.
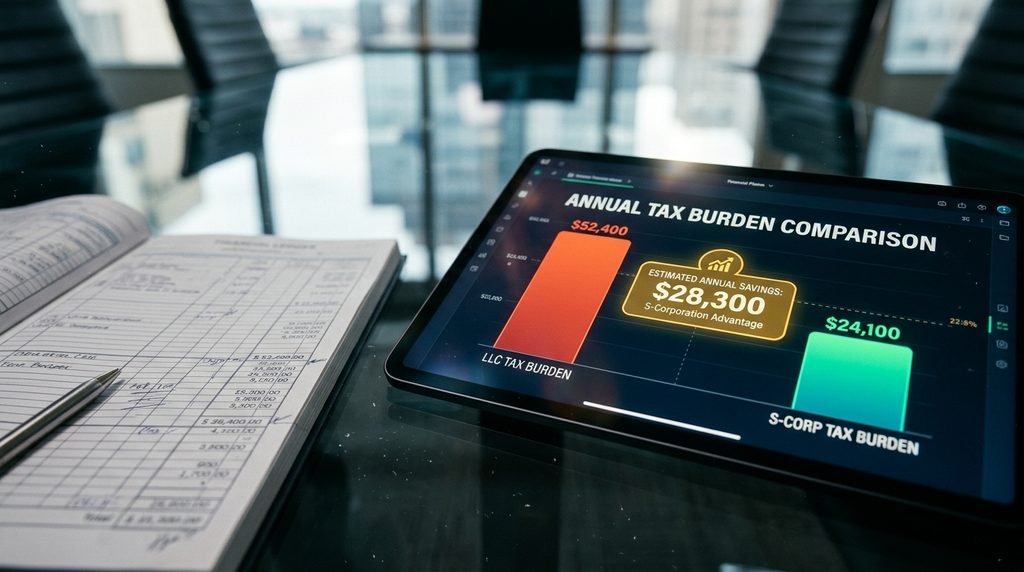
At the end of last year my colleague David, who looks after a high-net-worth portfolio at Horizon Financial Partners, asked me to carry out an audit of the corporate finance structure of a rapidly growing e-commerce business. The owner was making a net profit of $200,000 each year via a standard LLC. Since he had not restructured his company, the IRS had imposed on him a completely severe self-employment tax bill of $30,600, in addition to his usual federal and state income taxes.
We at once stopped him from following his present method of accounting. Through formally choosing S-Corporation status with the IRS and by reorganising the way his income was distributed, we reduced that particular tax liability to just $12,240. This one well-thought-out action immediately generated more than $18,000 in liquid self-employment tax savings for his business during a single fiscal year.
In order to help our agency clients get a clear picture of this particular financial restructuring, I have developed the Dixtify Free Calculator. This tool that is used inside the agency allows you to quickly compare the standard tax liability of an LLC with the improved payroll arrangement available through an S-Corporation. I am making it available free of charge today since it is entirely unnecessary to give the IRS a 15% tip on your hard-earned net profit. You need to guard your capital by carrying out ruthless corporate structuring.
The Brutal Reality of the LLC Tax Trap
If you really want to understand how this method works, then you need to examine the way standard small business taxation is structured. Upon setting up a basic Limited Liability Company (LLC), the IRS treats you as a ‘disregarded entity’; as a result, all the profit your business earns is passed directly to your individual tax return through Schedule C.
The issue isn’t merely the standard income tax; it’s the Federal Insurance Contributions Act (FICA). When employees receive a W-2, they pay 7.65% of their pay into Social Security and Medicare, and their employer contributes the other 7.65%.
With a standard LLC, you act as both the employer and the employee. The IRS then requires you to pay tax on both of these roles, which amounts to a heavy self-employment tax of 15.3% on your whole net profit. So, if your digital agency makes $100,000, you will have to pay $15,300 before looking at your actual federal income tax bracket. As a result, you are entirely unable to reinvest money back into your business.
Table of Contents
How the S-Corp Tax Loophole Actually Works
The entire S-Corp tax loophole changes the way the IRS treats your income, since an S-Corporation isn’t necessarily a new type of business; it is a special tax election that you make regarding your existing LLC by filing Form 2553.
After the election has been approved, you will cease to be regarded as a sole proprietor and will instead be classified as a W-2 employee of your own company. This is the key point of the whole strategy since it enables you to divide your business profits into two completely separate categories: a W-2 salary and dividends paid to shareholders.
Splitting Income: Salary vs. Distributions
With the S-Corp arrangement, you establish a formal payroll system and pay yourself a salary. The FICA tax still applies to this W-2 salary at the rate of 15.3%. Nevertheless, any of the profit that remains in the business after your salary has been paid can be taken as a ‘shareholder distribution’.
The secret is that shareholder distributions are not liable for self-employment taxes; they are fully exempt from that 15.3% levy.
If your business makes $150,000 and you run it as a standard LLC, then you have to pay 15.3% tax on the full amount of $150,000. However, if you choose S-Corp status, pay yourself a formal salary of $60,000 and take the other $90,000 as a distribution, you will only have the 15.3% self-employment tax applied to the $60,000 salary. The $90,000 distribution is not subject to self-employment tax at all and thus saves you almost $13,700 at once.
The “Reasonable Compensation” IRS Requirement
You could look at the figures and reason to yourself, “I’ll just pay myself a salary of $1 and then take $149,999 as a tax-free distribution.” However, the IRS is very aware of this method, and if you try it, you’ll attract an immediate and vigorous audit.
According to federal tax law, S-Corporation owners who are actively involved in their business are required to pay themselves “reasonable compensation” for the work they do. The amount of this salary should be the same as what you would pay a stranger to carry out your particular duties in your own geographical area.
As stated in a set of compliance guidelines published by Forbes, the main reason why S-Corporations incur heavy financial penalties is that they fail to carry out proper payroll and pay a reasonable salary. The IRS will then reclassify your tax-free distributions as wages and impose back taxes, penalties, and substantial compounding interest.
Defining Your W-2 Salary Safely
To work out what a safe salary would be you need to consider the particular role you have. For example, if you are running a high-volume dropshipping business and put in 40 hours a week on advertising and sourcing products, then you should look into the average salary for an e-commerce manager in your state.
A large number of conservative CPAs adopt a 60/40 or 50/50 rule as an approximate starting point, consisting of allocating 50% of your net profit to your W-2 salary and the other 50% to distributions. Although this rule is not a statute set out by the IRS, it usually keeps you safe from being selected for an audit.
If you’d like a professional consultation regarding the way in which you structure your corporate payroll or about putting into practice aggressive small business tax strategies, you can look at our custom growth strategies here: [Insert Internal Link to Dixtify Services].
Hidden Costs of Corporate Finance Structuring
This strategy is not something that can be carried out easily. If you are going to proceed with your S-Corp election, you must take into account the heavy administrative duties involved in keeping up the corporate veil. An S-Corp demands a great deal more accounting diligence than a simple LLC.
You can’t just move money from your business checking account to your personal one whenever you like. In order to pay yourself a W-2 salary you have to use official payroll software, for example Gusto or ADP, which charges you a monthly subscription fee and requires you to send the payroll taxes to the government every quarter.
Second, your corporate finance arrangement becomes more complicated. You have to file your corporate tax return (Form 1120-S) before you file your personal one. This means that you will need to hire an experienced CPA, the cost of which will be between $1,500 and $3,500 per year solely for tax preparation.
When Is the Right Moment to Pull the Trigger?
The S-Corp tax loophole isn’t worthwhile for new businesses because of the extra payroll fees and the cost of employing a CPA. When the only profit your side hustle makes is $30,000 each year, the administrative expenses involved in operating an S-Corp will entirely cancel out any tax benefits you might have.
The mathematical break-even point usually happens when net profit reaches between $60,000 and $80,000. After your business has been consistently above this figure, the savings from not having to pay self-employment tax become so large that they more than pay for the cost of payroll software and your accountant’s fees, leaving you with thousands of dollars in pure profit.
You should apply to your tax strategy the same aggression that you apply to your marketing strategy; restructuring your corporate entity is in fact the highest return on investment move that a profitable founder can make.